By W.A. Wijewardena –

Dr. W.A Wijewardena
Multilateral lenders such as the International Monetary Fund (IMF) and the World Bank continue to commend Sri Lanka’s recovery from the devastating crisis of 2022. From their macroeconomic—or bird’s-eye—view, the picture looks encouraging. Budgetary numbers are improving, reforms are progressing, inflation remains in single digits despite recently exceeding the Central Bank’s upper limit, foreign reserves are rising, and economic growth of 5% suggests a firm recovery. To international donors and local policymakers, the message is reassuring: the economy is stable and growing.
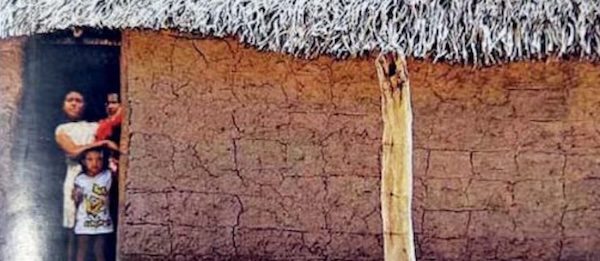
Lower the gaze to the ground, however, and the worm’s-eye view is strikingly different. Macroeconomic indicators cannot capture the hardships endured by ordinary people. Economics is not merely about aggregates; it is about human lives. Seen from above, a tree may display a flourishing green canopy. Examined leaf by leaf, it may reveal diseases quietly consuming it.
This problem is not new. In ancient Lanka, courtiers often assured kings that their subjects were content while concealing their hardships. Wise rulers therefore travelled through villages at night in disguise, discovering conditions for themselves and addressing grievances before they threatened the realm.
Ignoring today’s ground reality carries a similarly heavy price. People burdened by silent discontent become easy prey for opportunistic politicians, fraudulent operators, and pyramid schemes that exploit financial distress. The Government cannot afford to disregard this danger.
Looking at typical ground-level cases
Macroeconomic data alone cannot reveal conditions at ground level. A close examination of cases involving frustrated citizens shows discontent that official statistics rarely capture but that dominates the daily lives of many families.
Three broad causes recur: corrupt private-sector practices that cheat consumers and workers; public-sector failures that subject citizens to needless hardship; and banking rigidities that drive vulnerable borrowers into the hands of loan sharks.
Because these grievances are seldom assembled into formal macroeconomic assessments, they often fail to reach policymakers. The result is a dangerous disconnect between reassuring economic indicators at the top and painful realities at the bottom.
Poor governance in private sector
The private sector, widely regarded as the engine of growth in Sri Lanka, contributes more than three-quarters of the country’s national wealth. Yet, unresolved governance failures in some businesses leave workers and consumers vulnerable. Two examples illustrate the problem: the exploitation of young workers by small garment factories operating outside Colombo, and the defrauding of customers by corrupt insurance agents.
In the first case, a young woman—call her Janet—is recruited as a new employee by an outstation garment factory. Her letter of appointment promises a fixed salary and a monthly incentive if she meets her production targets. At the end of her first month, however, no wages are credited to her bank account. When she asks why, she is told that a computer-system failure caused the delay and that payment will be made once the system is restored. The same thing happens at the end of the second month. Unable to endure the situation, Janet complains to the head office, where an officer informally tells her that such non-payment is common at the factory. She later learns that the managers have been withholding the wages of new recruits and pressuring them to leave before the practice is exposed. Following her complaint, Janet receives part of her back pay, but she resigns because she can no longer work under managers whose misconduct she has reported. The managers thus achieve their apparent objective: forcing another new employee to leave. Because they consistently meet their production targets, the head office has also turned a blind eye to their corrupt practices.
The second case concerns corrupt insurance agents at major insurance companies who exploit the three-month credit window available when arranging a policy. This practice is particularly common in motor-vehicle insurance. A vehicle owner pays the premium to an agent, but instead of remitting it to the insurer, the agent pockets the money. The agent then issues documentation that appears to provide cover for a full year, although the policy is valid for only three months. The fraud usually comes to light only after the vehicle is involved in an accident and the owner submits a claim. By then, the policy has lapsed. Although insurance companies may be aware of this misconduct, they sometimes fail to act because the offenders are high-performing “golden agents”.
These cases demonstrate how poor governance can persist in both small and large private businesses. In each instance, commercial success shields misconduct, while workers and customers bear the cost. Such abuses may remain invisible in national accounts, but at ground level they cause severe financial and personal hardship.
Silent suffering of silvering people
Senior citizens—many now visibly silver-haired—are another group suffering silently at ground level. Their number, estimated at 3.92 million, or about 18% of the population, continues to grow. Traditional family support has weakened as children migrate abroad or, even when living in Sri Lanka, struggle with pressures of their own families and workplaces. Many older people must therefore rely largely on savings accumulated during their working lives. Yet the interest income on which they depend is subject to taxation of up to 36%, substantially reducing their disposable income. When they spend what remains on daily necessities and medical care, it is eroded further by indirect taxes and the high cost of living. Government support is limited, while pensions and other fixed incomes do not rise in step with the Central Bank’s inflation target of 5%, with an upper limit of 7%—a limit that can be breached when external shocks strike. It is reported that even the Central Bank’s own retirees, once among the country’s more secure pensioners, now feel these pressures. Their experience illustrates the article’s central contrast: a recovery that appears stable from the bird’s-eye view may still leave many senior citizens facing severe insecurity at the worm’s-eye level.
Government failures or inefficiencies
In some areas, the Government sector performs remarkably well. Sri Lanka Customs and the Inland Revenue Department, for example, have met revenue targets assigned by the budget, demonstrating that public institutions can deliver when goals, systems, and accountability are clear. Elsewhere, however, failures and inefficiencies cause immense hardship. Sri Lanka is rightly proud of maintaining free healthcare and education for decades. These services have expanded opportunity and social welfare, yet weaknesses in their day-to-day delivery provoke widespread public outcry. Citizens value the principle of universal provision but suffer when the institutions established to honour that principle cannot provide timely, dependable service.
In Government hospitals, shortages of basic facilities leave patients distressed. A patient may receive an appointment for critical surgery, make the necessary family and financial arrangements, and enter a major hospital expecting treatment. Only after admission may the operation be postponed because a surgeon, essential medicine, or vital machine is unavailable. The delay is not merely administrative: it prolongs illness, increases uncertainty, and may impose additional travel and living costs on the family. Wards are frequently overcrowded, beds are scarce, and some patients remain standing for hours while waiting for attention. Doctors, nurses, and other staff may work under severe pressure, but the citizen experiences the institution as a whole. A service intended to protect people at their most vulnerable can therefore add pain and uncertainty.
Schools suffer similar weaknesses. Students often complain that teaching in mathematics, information technology, and physics is difficult to understand during normal classroom hours. Because success at national examinations shapes access to higher education and employment, parents cannot simply wait for the system to improve. They purchase private tuition, sometimes through costly home visits by the same teachers responsible for those subjects at school. In effect, the principal learning support shifts from the publicly funded classroom to a private transaction. Such tuition can absorb nearly half the monthly income of a typical middle-class family, forcing sacrifices in food, healthcare, savings, and other essentials. Families thus finance free education through taxes and then pay again for the instruction their children need. The burden is even harsher for poor households that cannot afford supplementary teaching at all.
Administrative delays compound the burden. Vehicle owners may wait 15 months after registration for official number plates, despite having completed the required procedures and payments. Until the plates arrive, they face uncertainty in using or transferring their vehicles. Drivers who pass the prescribed tests may likewise fail to receive permanent licences because cards are unavailable. Temporary arrangements do not remove the inconvenience or anxiety caused by the State’s inability to issue a basic document. These may seem minor problems from above, but at ground level they consume time, disrupt daily life, and expose law-abiding citizens to needless uncertainty.
The police are also criticised for failing to pursue petty robbers and those engaged in roadside intimidation. Drug addicts seeking easy money sometimes stage minor accidents involving elderly or female motorists and then demand payment, relying on fear and confusion to secure a quick settlement. Victims may provide motorcycle registration numbers or photographs of alleged offenders, yet their complaints can meet with inaction. To an institution dealing with grave crimes, each incident may appear small. To the victim, however, it is a direct threat to personal safety and confidence in the law. Repeated inaction signals to offenders that vulnerable road users are easy targets. Such failures erode trust in law enforcement and deepen the sense that ordinary citizens must protect themselves.
These failures inflict pain that aggregate statistics cannot measure. Citizens judge the State by whether a hospital performs a scheduled operation, a school teaches effectively, a department issues an essential document promptly, and the police respond when help is sought. When basic services fail, the worm’s-eye view remains far less reassuring than the bird’s-eye view.
Underhand payments to petrol-pump operators
Even well-intentioned regulations can backfire when they ignore behaviour at ground level. Sri Lanka introduced a Quick Response (QR) code to ration petrol and diesel during a period of scarcity, limiting most motorcars to 25 litres a week. An odd-and-even date rule tied eligibility to registration numbers and was intended to control queues and distribute limited supplies fairly. Yet many motorists found the quota inadequate for commuting and essential travel. The date restriction created a further difficulty: an empty tank on the wrong day could leave a driver stranded even when fuel was available. A rule designed at the centre for orderly allocation thus created powerful incentives for evasion at the pump.
The system consequently gave fuel-pump operators power to profit from desperation. A motorist facing urgent travel could make an underhand cash payment, after which the restrictions suddenly became flexible. An operator who controlled access to the pump could manipulate the process and dispense fuel beyond the weekly quota, even on an ineligible day. Compliance therefore depended not only on technology but also on the integrity of those implementing it. When implementation is weak, a digital rule can merely shift discretion—and the opportunity for corruption—to another level.
A mechanism intended to ensure equity thus bred ground-level corruption. Money that should have entered the revenues of State or private petroleum companies flowed instead into individual pockets. Honest motorists either accepted inadequate supplies or paid bribes to overcome the restrictions, while those with connections or cash obtained more. Ordinary citizens were pushed towards misconduct merely to meet transport needs, widening the gap between clean digital models and compromised daily reality.
Banking rigidity drives the desperate to loan sharks
Financial literacy and inclusive banking also function poorly at ground level. Despite claims of wider outreach and sophisticated technology, formal institutions classify many small borrowers as non-bankable because they lack acceptable collateral, regular income records, or conventional credit histories. Yet these borrowers include traders and self-employed people whose livelihoods require small amounts of working capital. Commercial banks do little to build their capacity, monitor them closely, or bring them gradually into the formal system. When they urgently need funds to buy business stock, meet school expenses, or handle a medical emergency, they cannot wait through lengthy procedures. They are driven instead to informal moneylenders who ask few questions and provide cash immediately.
That convenience carries ruinous terms. Loans may have maturities as short as 100 days, with interest collected daily and amounting to as much as 10% a month. Daily collection makes each payment appear manageable, but the cumulative charge absorbs a large share of the borrower’s earnings. At maturity, the principal is commonly rolled over on the same terms because the borrower has been unable to save enough to repay it. A temporary cash shortage is thereby converted into perpetual debt, and income that should sustain a family or expand a microenterprise is transferred continuously to the lender.
The exploitation thrives in the absence of strict, modern usury laws and effective enforcement. Even the historic Ultra Duplum rule—which limits accumulated interest to the original principal—is bypassed or poorly enforced under the century-old Money Lending Ordinance and newer microfinance regulation to be enforced under the recently enacted Microfinance Regulatory Authority Act. Vulnerable borrowers rarely possess the knowledge, records, time, or resources needed to challenge abusive terms. The resulting anger is widespread in rural and urban communities. As the economics writer Yadamini Gunawardena observed by coining the term “The 5km Blind Spot”, such exploitation occurs within five kilometres of Colombo’s skyscraper-filled financial district—a systemic failure under policymakers’ noses. Financial inclusion cannot be measured only by the number of bank branches, accounts, or digital applications; it must also be judged by whether citizens can obtain safe, affordable credit when they need it.
Ground-level distress, a matter for concern
Taken together, these ground-level realities reveal a fractured recovery. The bird’s-eye view of lenders and policymakers shows fiscal discipline, single-digit inflation, rising reserves, and renewed growth. The worm’s-eye view shows ordinary citizens squeezed by private corruption, public-sector failure, arbitrary regulation, and financial exclusion. Macroeconomic stability is essential, but it is not sufficient if people continue to experience insecurity, exploitation, and ineffective public services. This ‘not-so-rosy picture’ is the breeding ground for social, economic, and political disorders that will disable overnight, as happened in 2022, the much-praised stable and growing economy.
*The writer, a former Deputy Governor of the Central bank of Sri Lanka, can be reached at waw1949@gmail.com