By Sugath Amarasekera –
Sugath Amarasekera
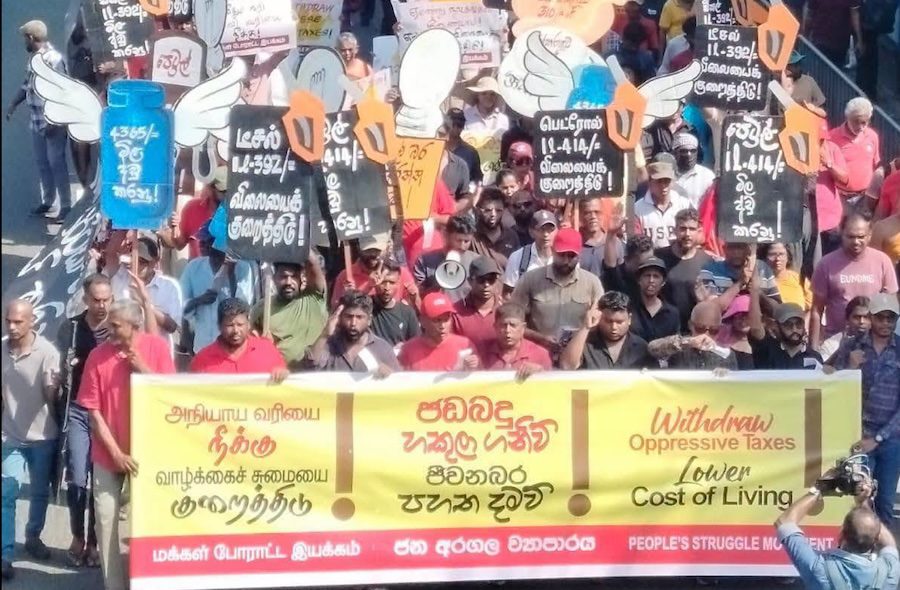
The protest march organised yesterday by the Front Line Socialist Party (FLSP) was, in my view, failed to deliver clear message to the govt—not necessarily because the grievances were wrong, but because the protest failed to articulate a credible economic alternative.
The central issue confronting working class people today is not simply that taxes are high. It is that the entire economic adjustment has placed an enormous burden on household purchasing power while failing to create the conditions necessary for sustained expansion of productive capacity, employment and incomes.
That is the argument the FLSP should have taken to the streets.
The real burden is falling on household demand
A very large proportion of Sri Lankan households- more than 75% per CBSL statistics, I have monthly incomes below Rs.75,000. These families spend most, if not all, of their income on essential goods and services. Indirect taxes therefore consume a disproportionately large share of their purchasing power.
Even middle-class households are increasingly living from one pay cheque to the next, with little disposable income after paying for food, transport, electricity, education, housing and other necessities.
The result is predictable: tax revenue can rise while domestic purchasing power simultaneously falls.
This distinction is critical.
Sri Lanka’s government revenue performance has improved substantially. Revenue and grants reached 16.7% of GDP in 2025, according to the IMF, while the government has been pursuing a medium-term objective of maintaining revenue above 15% of GDP.
That is not, in itself, something to criticise. A state needs adequate revenue to provide public services, invest in infrastructure and meet its debt obligations.
The problem is how that revenue is being collected and what the resulting fiscal adjustment is doing to the real economy.
When a large proportion of additional revenue is extracted from households that already have very limited disposable income, the state may improve its fiscal accounts while simultaneously weakening domestic demand.
That is the contradiction the FLSP should be exposing.
The debt burden makes tax reduction difficult
The government’s predicament is real.
Interest payments alone are projected to absorb roughly half of government revenue in 2026. The 2026 budget estimate puts interest expenditure at approximately Rs.2.62 trillion, with the interest-to-revenue ratio around 49%.
This leaves the government with extremely limited fiscal space.
Consequently, simply demanding that the government reduce VAT and other taxes is not an adequate economic programme.
The obvious question is: if taxes are to be reduced, how will the government replace the revenue and meet its debt obligations?
That is where the political debate should begin.
The answer cannot simply be more borrowing from the domestic market. Excessive reliance on market borrowing can keep financing costs elevated and crowd out productive private investment.
The answer must instead involve a restructuring of the government’s domestic debt-service burden, a reduction in excessive interest costs, and a deliberate strategy to redirect financial resources towards productive investment.
The extraordinary cost of domestic borrowing must be confronted
During the economic crisis, Sri Lanka’s government securities traded at extraordinarily high yields.
Central Bank data show that in 2023 primary-market Treasury-bill yields reached above 32%, while some Treasury bonds traded above 30%.
These exceptionally high rates were a product of the crisis conditions and the government’s desperate need for financing.
But today’s taxpayers should not be expected indefinitely to carry the consequences of exceptionally expensive borrowing undertaken under crisis conditions.
The government should therefore undertake a comprehensive examination of the domestic interest burden, including the distribution of interest payments, the maturity structure of government securities and the returns earned by financial institutions that accumulated government securities during the crisis.
If a substantial portion of current interest expenditure is attributable to securities issued at exceptionally high crisis-era yields, there should be a serious discussion about whether those obligations can be refinanced, extended, exchanged or otherwise restructured without destabilising the financial system.
This is a far more meaningful target for a socialist political movement than simply demanding that the government cut taxes.
The FLSP should be asking:
Why should working people bear the full burden of taxation to service extraordinarily expensive government debt accumulated during a national financial crisis?
That is a question capable of mobilising the public.
The economy cannot grow without purchasing power
The deeper problem is demand.
Businesses invest when they expect sufficient demand for the goods and services they produce.
But what happens when millions of households have experienced stagnant real incomes, high living costs and declining purchasing power?
Businesses become reluctant to expand capacity.
Why invest in another factory, another production line, another hotel, another retail outlet or another service business if consumers cannot afford to purchase the additional output?
This is the fundamental weakness in an economic strategy that concentrates almost exclusively on fiscal consolidation and macroeconomic stability.
Production and purchasing power must expand together.
If productive capacity expands without sufficient purchasing power, businesses eventually face unsold inventories and declining profitability.
If purchasing power expands without a corresponding increase in productive capacity, inflationary pressures can emerge.
The economic policy challenge is therefore to make income growth, productivity growth and productive capacity expand together.
That is what a serious development strategy should be designed to achieve.
Inflation cannot be understood simply as excess demand
The argument that Sri Lanka must suppress domestic demand to control inflation also requires greater sophistication.
A substantial component of Sri Lanka’s inflation problem has historically originated from external shocks—energy prices, imported food, exchange-rate movements, global commodity prices and other imported costs.
Such inflation is fundamentally different from an economy experiencing an excessive wage-driven demand boom.
If household incomes are stagnant while imported costs rise, suppressing domestic demand through high interest rates and heavy taxation can reduce economic activity without necessarily addressing the original source of the inflation.
The Central Bank’s own framework recognises that monetary policy affects household and business spending, investment and ultimately economic activity.
The question, therefore, is not whether monetary discipline is necessary.
It is whether monetary and fiscal policy are sufficiently calibrated to support productive investment and employment while maintaining price stability.
What is the Central Bank’s responsibility?
The Central Bank cannot be responsible for every aspect of economic development.
But neither should it behave as though economic growth is someone else’s problem.
Price stability is essential. Financial stability is essential. Exchange-rate stability and rebuilding reserves are important.
But these objectives ultimately exist to support the functioning and development of the real economy.
A country does not become prosperous merely because inflation falls, reserves rise and government borrowing declines.
It becomes prosperous when its people have productive employment, rising real incomes, affordable goods and services, increasing productivity and expanding opportunities.
The Central Bank therefore needs to engage much more deeply with the question of how monetary conditions affect productive investment.
The issue is not simply whether interest rates are high or low.
The question is:
Are financial resources flowing towards activities that expand Sri Lanka’s productive capacity, productivity and export potential?
That should be one of the central questions in the country’s economic policy debate.
The FLSP should demand a productive economic programme
This is why I believe the FLSP’s protest should have been fundamentally different.
Instead of simply demanding:
“Reduce taxes!”
it should have demanded:
“Restructure the debt burden, protect household purchasing power and redirect finance towards productive investment.”
That is a programme.
The FLSP should demand:
A comprehensive review of domestic government debt and crisis-era interest costs.
Restructuring or refinancing of excessively expensive domestic debt wherever this can be done without destabilising banks, pension funds or the wider financial system.
A reduction in the government’s interest burden, creating fiscal space to reduce the most regressive taxes.
A shift from indirect taxation towards a more progressive tax structure, consistent with the government’s own stated intention to improve the direct-to-indirect tax balance.
A major programme of productive credit, directing finance towards manufacturing, agriculture, technology, energy, exports and other activities that increase domestic productive capacity.
A deliberate strategy to raise productivity, so that goods and services can be produced at prices compatible with the purchasing power of ordinary Sri Lankans.
A coordinated income-and-productivity strategy, ensuring that rising household incomes are accompanied by expanding productive capacity.
A new approach to monetary policy, in which price stability remains essential but monetary conditions are also evaluated according to their impact on productive investment and employment.
Negotiations with the IMF on the policy space available for growth-oriented monetary and fiscal measures.
What about money creation?
There is also a legitimate debate to be had about monetary expansion.
But it must be conducted intelligently.
Sri Lanka’s current legal and IMF framework prohibits conventional monetary financing of the government. The IMF programme explicitly monitors the ceiling on Central Bank net credit to government and prohibits Central Bank purchases of government securities in the primary market.
That does not mean Sri Lanka should abandon the debate.
It means the debate should be about whether the present framework provides sufficient monetary policy space for a recovering economy.
If Sri Lanka achieves sustained real economic growth of around 5%, maintains inflation under control and expands productive capacity, there should be a serious examination of whether a carefully calibrated expansion of the monetary base—perhaps equivalent to around 1–1.2% of GDP under strictly defined conditions—could support productive investment without generating excessive inflation.
Such monetary expansion should never be used simply to finance recurrent government expenditure.
It should be tied to measurable increases in productive capacity, employment, exports, energy production, food production and technological investment.
That is fundamentally different from indiscriminate money printing.
The debate should therefore be about productive monetary expansion, not simply “printing money”.
Sri Lanka needs a different political-economic conversation
Sri Lanka cannot escape its debt burden by pretending it does not exist.
Nor can it escape poverty by simply increasing taxes.
And it cannot build a prosperous economy by concentrating exclusively on reserves, fiscal targets and debt sustainability while allowing household purchasing power and productive investment to remain weak.
Macroeconomic stability is a necessary condition for development.
It is not development itself.
The IMF’s own current projections put Sri Lanka’s real growth at around 3% in 2026, after 5% growth in 2025. The IMF has also stressed the importance of investment and reforms capable of raising Sri Lanka’s long-term growth potential.
The country therefore needs to move from a narrow stabilisation strategy towards a genuine development strategy.
That is where the FLSP—and indeed every serious opposition political force—should focus its energy.
The people do not need another protest merely telling the government that taxes are too high.
They need political movements capable of explaining why taxes are high, why debt-service costs are so high, who benefits from the existing financial structure, how the debt burden can be reduced, how productive investment can be financed, and how household purchasing power can rise without triggering another inflationary crisis.
That is the debate Sri Lanka desperately needs.
And that is the debate the FLSP should be leading.